Contents
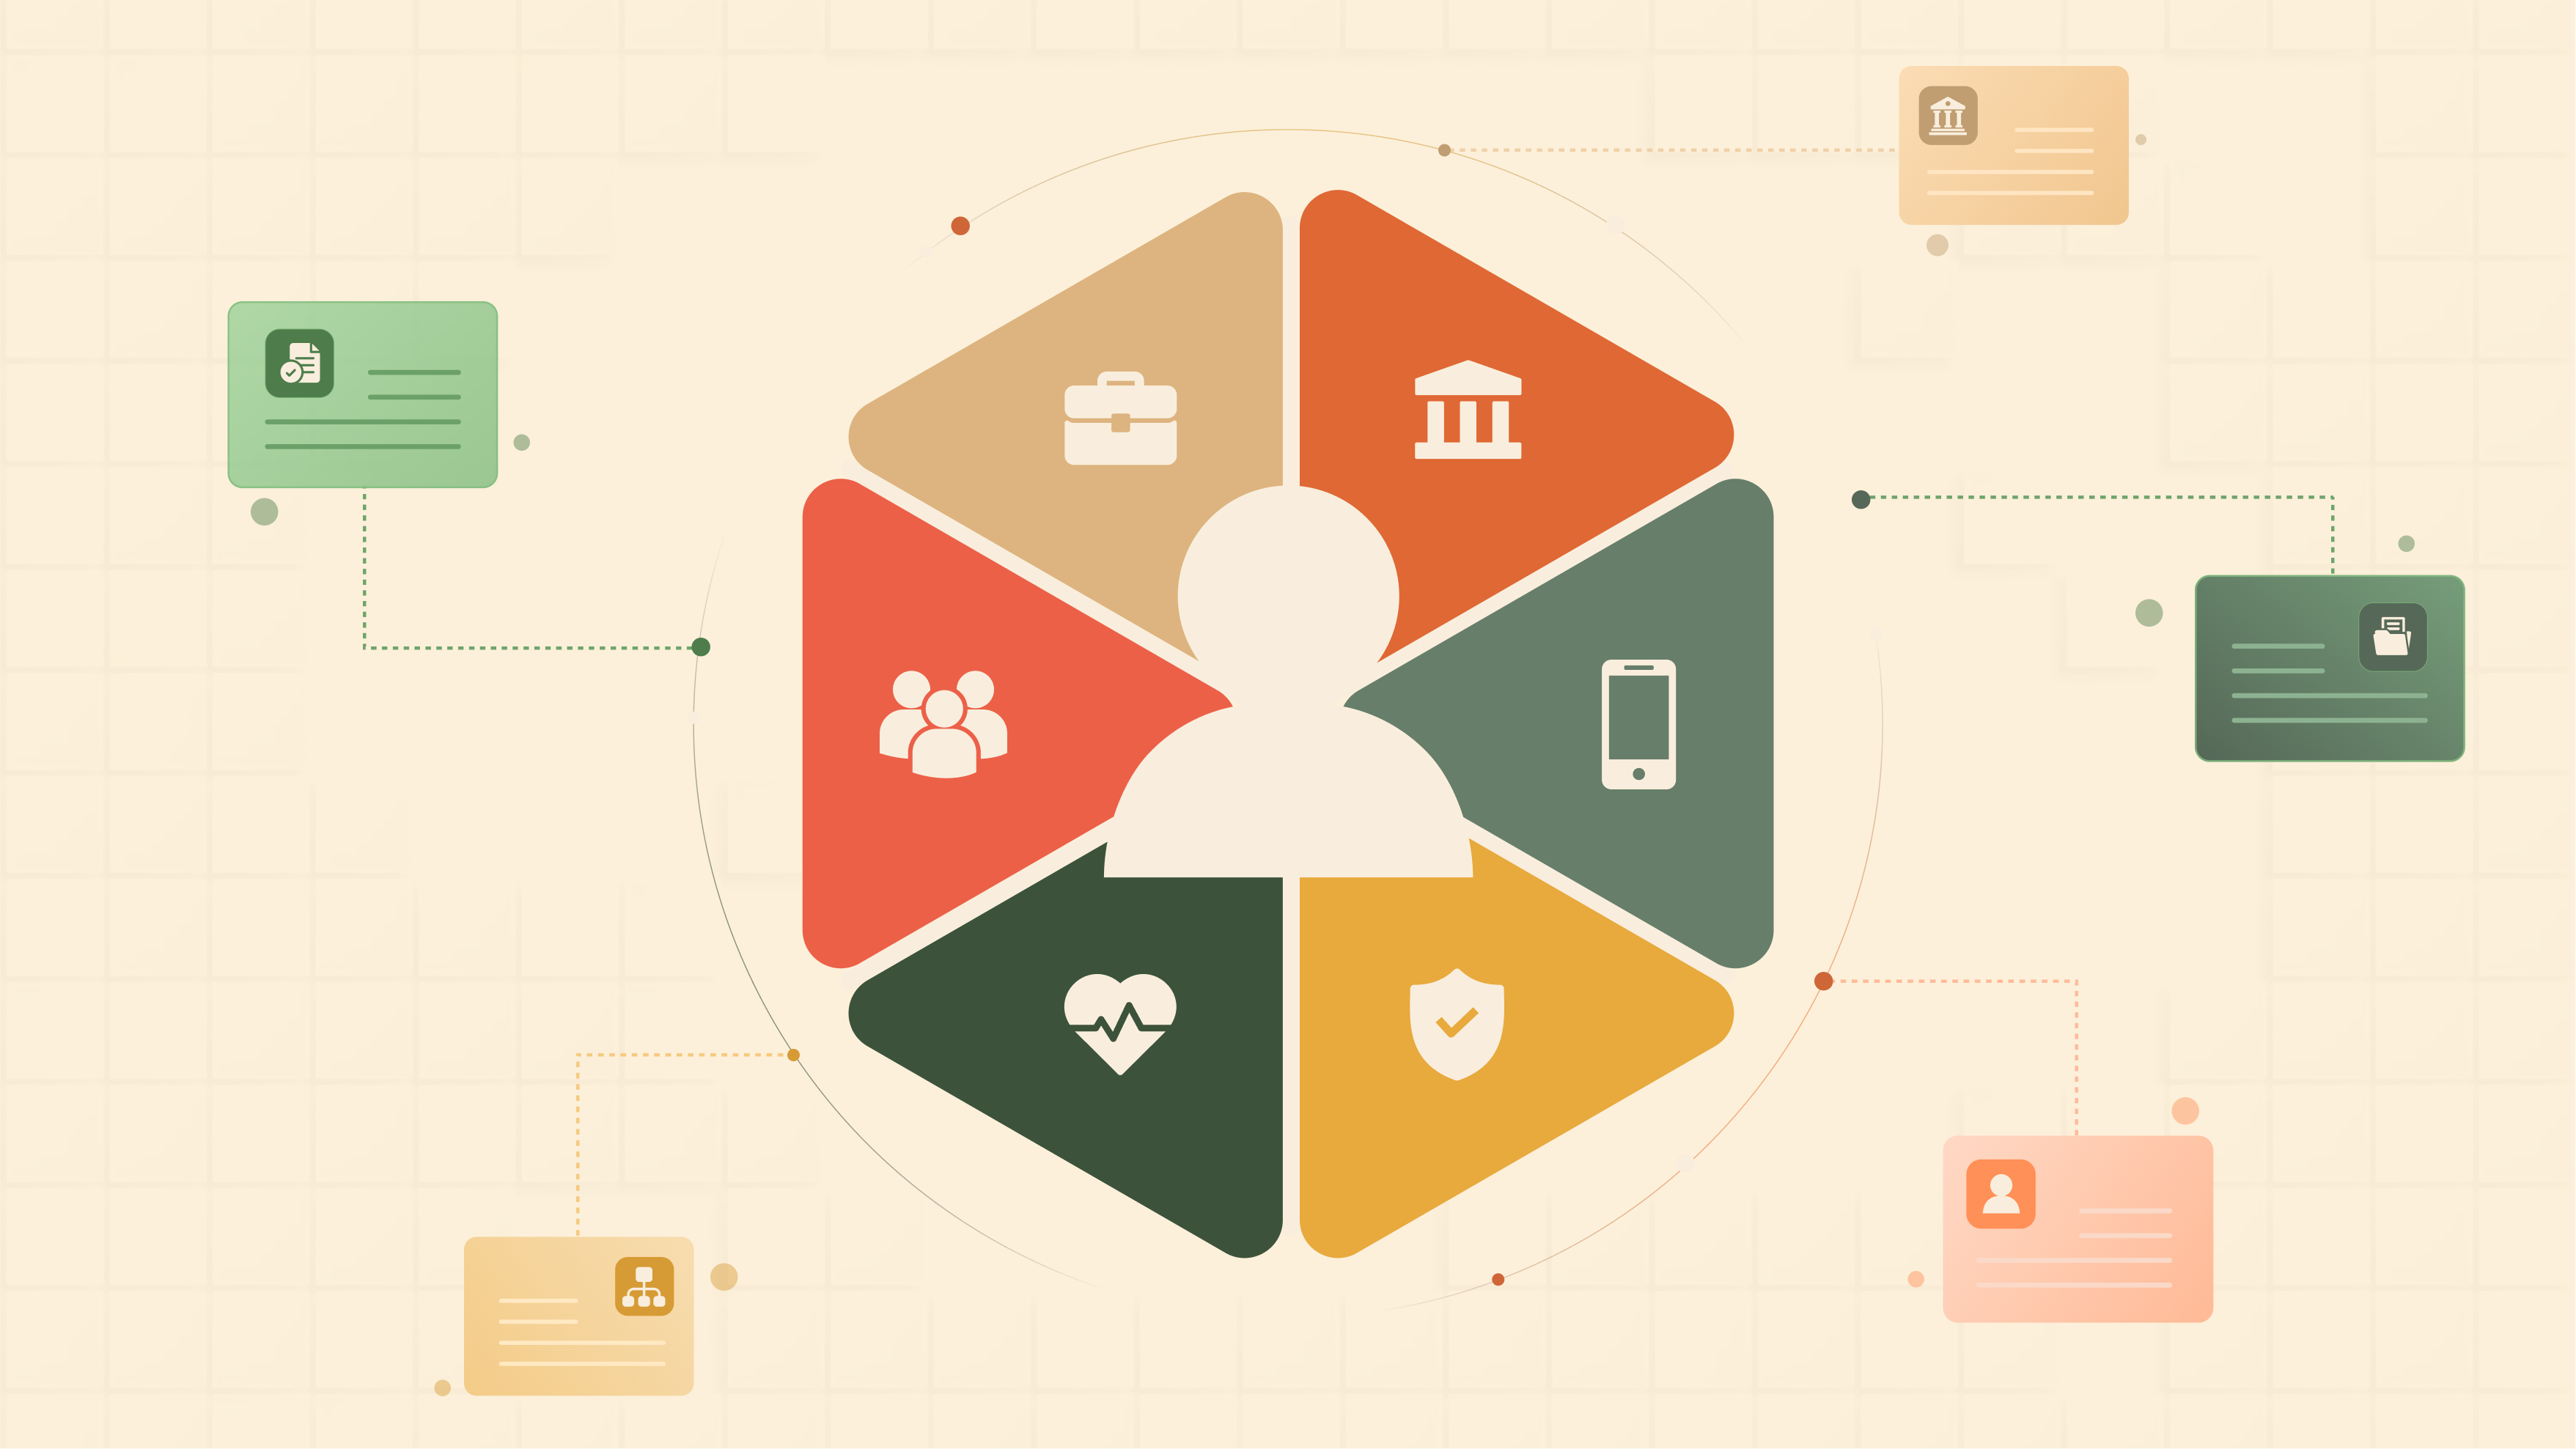
Insurance is bought one policy at a time, but a customer’s real protection accumulates across multiple fragmented relationships. Health cover may come through an employer alongside a personal top-up; life insurance might sit with a public sector legacy provider; loan protection attaches to a home loan; and device protection gets bundled at a retail checkout.
While every issuing institution maintains its own records, the customer’s complete coverage profile remains scattered. When the time comes to make the next financial decision, neither the customer nor the distributor has a complete picture.
IRDAI's proposed Public Insurance Registry (PIR) is intended to address part of this information challenge through an interoperable digital infrastructure for insurance. The consultation paper envisages authorised participants—including insurers, intermediaries, reinsurers, financial institutions, government entities and policyholders—being able to access and exchange relevant insurance information, while the underlying records remain with the institutions that hold them.
While much of the discussion around PIR focuses on regulatory compliance and data architecture, we believe its true impact lies in a fundamental operational question: What happens to insurance distribution when a customer’s complete protection context becomes visible at the point of recommendation?
From Policy Sales to Need-Gap Advisory
Insurance is ultimately a product of context. The suitability of a new policy depends partly on what protection is already in place, the extent of that protection and the risks that remain uncovered.
Mayank Gupta, Co-founder & COO of Zopper, sees this as one of the practical questions that a Public Insurance Registry could address:
As an intermediary, we are always advising clients on which insurance product is best suited for them and that requires understanding of how much coverage they already have. Often customers lose track of or forget which all covers they are already eligible for, and as a result end up buying multiple coverages on same risks and leave some risks fully uncovered. A central repository of all insurance plans will help a user in assessing need gap in a very efficient manner and help in planning incremental coverage more appropriately.
The point is not that every customer needs more insurance, or that an insurance recommendation should automatically become a function of the information available through PIR. It is that existing coverage is part of the context in which the next recommendation is made. If that context becomes easier to establish, it could influence how intermediaries assess incremental protection.
This has implications for the way insurance distribution operates across channels.
Channel Impact: Bancassurance vs. Embedded Networks
The availability of shared, consent-backed insurance data fundamentally could alter how different distribution channels operate.
1. Bancassurance & Bank-Led Channels
Banks and NBFCs already have a substantial financial relationship with their customers. Insurance is increasingly part of that relationship, but insurance information can still sit across multiple insurers and distribution systems.
A more interoperable insurance information framework could give authorised financial institutions another source of context when insurance becomes part of a broader customer conversation. A relationship manager considering a protection product could, subject to the eventual access and consent framework, have a better understanding of what cover already exists before discussing additional insurance.
2. Embedded Insurance Platforms
Embedded insurance places protection within a journey that may originate outside a traditional insurance interaction—a purchase, a loan, a financial service or another customer transaction. The challenge for the platform is not simply whether insurance can be offered at that point, but whether the protection being offered is relevant to the customer's circumstances.
The context from PIR data would potentially allow embedded technology platforms to dynamically suppress redundant offers and instead surface hyper-relevant add-ons, increasing conversion rates while preserving customer trust.
The Tech Infrastructure Shift: How Middleware Evolves
Creating an interoperable information framework does not remove the systems that insurers, banks, NBFCs, intermediaries and technology providers already operate. Those systems still have to exchange information, interpret it and incorporate it into customer and operational workflows.That brings insurance APIs, data standards, identity, consent and authentication into the discussion.
The IRDAI consultation (deadline extended to 17th October 2026) seeks views on precisely these areas, including data architecture, data standards, identity frameworks, privacy, consent, security and governance. These choices will determine not only what information can be accessed, but under what circumstances and in what form it can be used.
For B2B insurance technology and distribution platforms like Zopper, the implementation of PIR accelerates a core strategic evolution:
- From API Plumbing to Context Engines: Historically, insurtech middleware served primarily as transactional plumbing—routing application data between distributor interfaces and insurer underwriting engines. With PIR, middleware transforms into an active decision engine. It queries the registry in real-time, calculates protection shortfalls, and dynamically renders the appropriate product configuration.
- Streamlined Underwriting and Reduced Drop-Offs: Manual non-disclosure disclosures often cause underwriting delays, counter-offers, or policy rejections. By passing verified, pre-existing coverage data straight to underwriting engines, tech platforms can minimize drop-off rates and enable instant policy issuance.
- Standardization Redefining Competitive Advantage: As IRDAI standardizes data formats, consent artifacts, and authentication protocols, simple backend integration becomes a baseline expectation. The competitive moat for technology platforms moves from merely holding carrier APIs to how intelligently their orchestration layers process registry insights to drive conversion.
Bridging the Gap to Customer-Centric Insurance
The insurance industry has traditionally organised information around policies, products and institutions. Customers experience insurance differently. They experience it as the total protection available to them and their families
That gap between policy-level information and customer-level context is where PIR could have its most interesting implications.
For intermediaries, it could inform how coverage needs are assessed. For banks and NBFCs, it could add another dimension to an existing financial relationship. For embedded insurance, it could provide context within a non-insurance transaction. For insurers, it could introduce new information into underwriting and servicing workflows. For technology providers, it could create a more standardised environment in which these systems interact.
None of these outcomes is automatic. They depend on the final regulatory architecture and, equally, on how participants choose to build around it. That is why the most important question may not be how much insurance information the Public Insurance Registry eventually connects. It may be how that information is used when the next insurance decision is being made.
If a customer, intermediary, bank, insurer or embedded platform can look beyond an individual policy and understand the broader protection position—with the appropriate consent and controls—the basis for that decision could be different. For an industry increasingly connected by digital infrastructure, that is a question worth examining alongside the registry itself.