Contents
From January 1, 2027, insurance policies sold through intermediaries will be required to carry details of the intermediary or authorised salesperson who solicited the policy. Proposal forms, policy documents and certificates of insurance will also carry the contact details of the relevant branch or office. For policies sold directly through an intermediary's digital platform, the contact details of the Principal Officer will need to be disclosed.
The immediate focus will understandably be on implementation.
However, for banks, NBFCs and other insurance distributors, the practical questions are likely to be more important than the announcement itself. How will seller information be captured across different journeys? What happens when a customer interacts with more than one channel? Will existing processes need to change? And how can institutions meet the requirement without adding unnecessary work for branches, relationship managers and sales teams?
These are reasonable questions. Insurance distribution has changed considerably over the years, and the journeys institutions operate today are very different from the linear models on which many earlier processes were built.
Seller tagging, therefore, is better understood not simply as a new disclosure requirement, but as part of a broader shift towards greater traceability and accountability at the point where insurance is solicited.
Why seller tagging has become necessary?
The growth of insurance distribution has been driven, in part, by the industry's ability to meet customers where they already are. Banks and NBFCs have integrated insurance into broader financial relationships. Relationship managers have become an important part of assisted journeys. Digital platforms have enabled customers to explore and complete transactions in new ways. Partnerships and embedded models have created additional points of access.
This expansion should be viewed as progress.
While this growth has increased market reach, it has also created a complex web of handoffs. A customer may first discuss insurance with a relationship manager, continue the journey digitally and receive a policy issued through an insurer's system. Another customer may encounter insurance alongside a loan, seek assistance later and complete the proposal through a different channel. As the number of journeys and handoffs grows, one question becomes increasingly important: how does the relevant accountability remain connected to the transaction?
Seller tagging seeks to create greater clarity around the person associated with the solicitation of a policy. Institutional accountability will continue to rest with insurers and intermediaries, but the policy will now carry an additional layer of visibility around the authorised individual or distribution channel involved in its solicitation.
For distributors, the significance lies not in the act of adding a name to a document, but in ensuring that this information can work across the way insurance is actually distributed today.
The implementation challenge should not become another layer of friction
The natural response to any new regulatory requirement is often to create a separate process around it. A new portal, an additional manual field or a reconciliation exercise once the transaction has been completed. That may address the immediate requirement. But the more important question is whether it is the most sustainable way to operate at scale.
Banks and distributors have spent years building multiple ways for customers to access insurance. It would be counterproductive if the response to greater accountability was to make every journey more rigid or introduce additional administrative work for authorised sellers. The customer journey should continue to remain flexible. An RM-led journey does not need to look like a self-service digital journey. A customer who begins online should still be able to seek assistance later. Different channels should be able to operate in ways that suit their customers and business models.
What needs greater consistency is the information and accountability framework behind those journeys.
The opportunity is to ensure that the relevant seller and transaction context is captured at the appropriate stage and remains connected as the journey progresses, rather than having to be recreated once the policy is ready to be issued.
Where the role of infrastructure becomes important
Most organisations have built their technology environments over many years. Customer management, distribution operations, proposal journeys, underwriting and policy administration all serve different purposes. At the same time, insurance distribution itself has expanded across bancassurance partnerships, intermediaries, digital platforms and other channels. As a result, an insurance journey may involve multiple systems and participants before a policy is ultimately issued.
As insurance distribution becomes more hybrid, there is growing value in infrastructure that can connect the different stages of the journey without requiring institutions to rebuild the systems and distribution models they already rely on.
This is where Zopper sees an important role for Zenova.
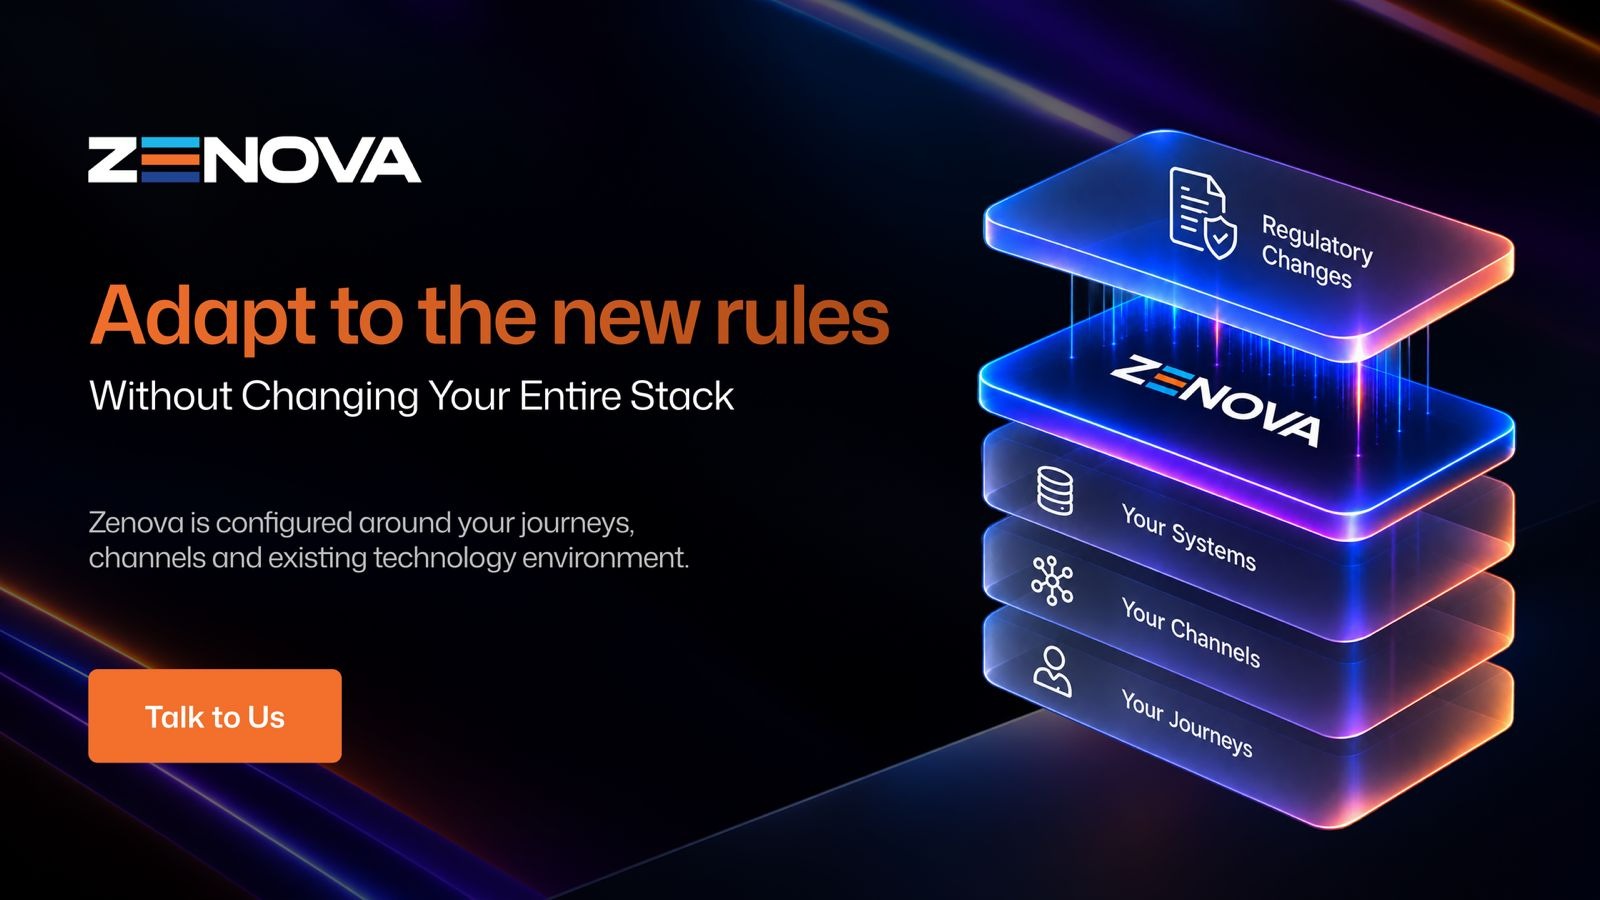
Zenova is designed to orchestrate the insurance journey across distribution channels and insurer systems, while bringing key stages of the sale—such as suitability, solicitation, disclosures, consent and evidence—into a connected transaction flow.
In the context of seller tagging, this matters because the identity of the person who solicited a policy is not the only information that may need to remain traceable. The sale itself can involve multiple stages before a policy is issued. By connecting these stages across existing distribution and insurer environments, Zenova can help institutions manage the journey around a sale as a more continuous transaction, rather than treating regulatory information as something that needs to be assembled separately at the end.
The next phase of insurance distribution
Seller tagging is an important regulatory development, but its long-term significance may extend beyond the information that eventually appears on a policy document. It raises a broader question for the industry:
As insurance distribution continues to become more flexible and multi-channel, how can accountability evolve without taking away that flexibility?
The answer is unlikely to be a return to simpler, more linear journeys. The diversity of today's distribution models is one of the reasons insurance can reach more customers. The opportunity instead is to ensure that as journeys become more complex, the information, controls and context associated with a transaction can remain connected through them. For banks, NBFCs, insurers and other distributors, this is not simply a question of adding another compliance process. It is increasingly a question of how distribution journeys are designed, orchestrated and managed across people, channels and systems.
Seller tagging may make the seller visible. The larger opportunity is to build insurance distribution that can adapt as journeys, regulations and customer expectations evolve—while preserving the context and accountability behind every transaction.